Near you, no matter where you are.
Appointed Representative of The Right Mortgage Network (FCA No. 1004260). Company No. 15189091. Registered in England and Wales.
Mortgage advice for buyers and homeowners in Farnborough, with specialist support for contractors and company directors. Compare suitable options from more than 90 lenders.
More than mortgages, we cover the whole journey
With access to over 90+ lenders
5 Star Reviews
In mortgages arranged for clients


Farnborough attracts commuters as well as people working in aviation, aerospace, defence and technology. That creates a broad mix of salaried, bonus-based and contract income. The housing market also ranges from town-centre and North Camp flats to family homes around Cove and Southwood, with new-build and leasehold criteria varying by lender.
We match both sides of the case. Your adviser reviews income, deposit, commitments and credit history, then checks the proposed property's tenure, construction and value. This is particularly useful for contractors whose day rate may be assessed differently across lenders, or buyers comparing homes in Farnborough with nearby Fleet, Aldershot and Camberley.
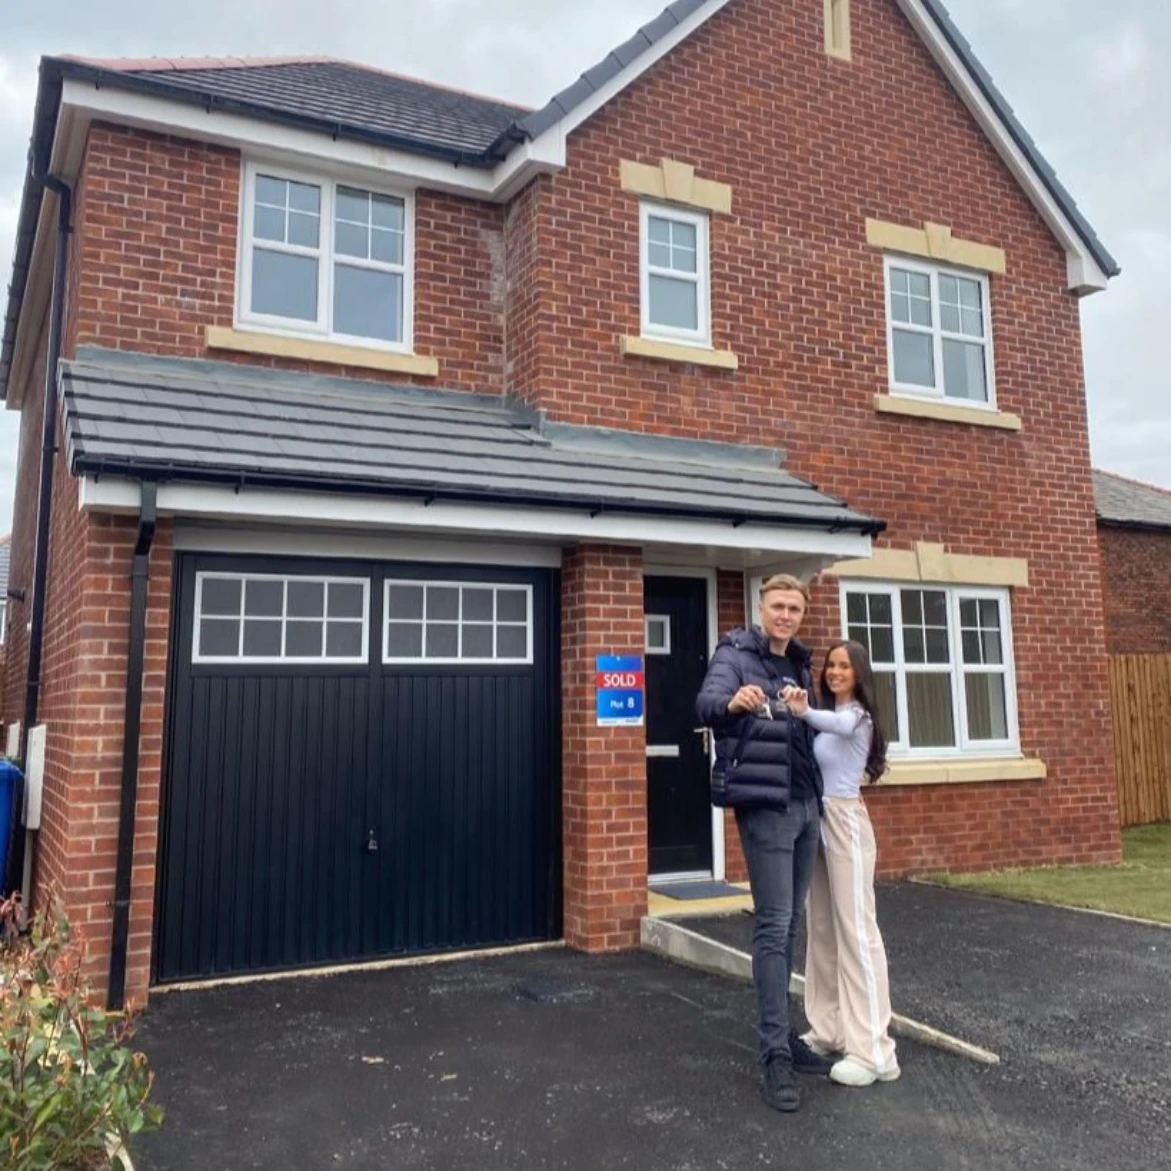
We support Farnborough residents buying their first home, moving, remortgaging or investing, with particular experience of contract and non-standard income.
We turn your income and deposit into a usable budget, arrange an Agreement in Principle and guide you through lender checks on the applicant and property.
We compare porting your existing deal with taking a new mortgage, account for early repayment charges and coordinate the finance with your property chain.
We help contractors, consultants, sole traders and company directors evidence income clearly and approach lenders whose criteria suit their working arrangements.
We advise new and established landlords on purchase and remortgage options, including limited company cases, subject to rental coverage and lender criteria.
MBNM gives Farnborough clients access to more than 90 lenders without requiring a branch visit. Advice is available by phone or video, with WhatsApp updates if preferred. Your adviser explains the lender criteria, compares suitable products, prepares the application and stays involved through valuation and underwriting. That is especially valuable when contract income or a less standard property needs to be presented carefully.
As an independent broker, MBNM has access to mortgage options from over 90 lenders, giving clients access to deals they won’t find by walking into a single bank.
We regularly handle applications involving self-employed income, remortgaging, buy-to-let properties, and time-sensitive purchases, situations where bank-only advice often falls short.
From your first conversation through to mortgage offer, we handle paperwork, lender queries, and follow-ups, keeping things moving and keeping you informed.
MBNM is FCA regulated and focused on clear, jargon-free advice. No sales pressure, no hidden agendas, just guidance that makes sense for your goals.
The process begins with a conversation about your objective, income, deposit and target property. We check affordability and lender criteria, compare suitable products and arrange an Agreement in Principle when required. We then prepare the application, manage lender questions and keep you updated until the mortgage offer is issued.
We start with a straightforward conversation to understand your situation, goals, and timeframe. This helps us assess affordability, lender criteria, and the most suitable mortgage options from the outset.
We compare mortgages across the whole market, reviewing rates, terms, and lender requirements to find an option that fits your circumstances, not just what’s easiest to place.
Once you’re happy, we manage the full application process. That includes paperwork, lender questions, and follow-ups, keeping things progressing without unnecessary delays.
When your mortgage offer is issued, we guide you through the final steps and coordinate with solicitors or agents as needed, right through to completion.
If you have a question, please do not hesitate to reach out!
Tell us what you are planning and we will explain the next step. Your first chat is free and appointments are available by phone or video, with WhatsApp updates if preferred. If we can help, any fee will be explained and agreed before work begins.
"After speaking to another broker and being told we had to wait longer to get a mortgage, we landed on Will’s page! We had a unique self employed situation but Will instantly knew how to work our figures and although we weren’t in a position to buy straightaway, Will has given us a path and steps to what we need to make buying our home possible! There is never a straight no from Will, it’s always a ‘not now, but when’. Highly recommend for anyone looking for a mortgage broker in the UK"
"Smoothest process I’ve experienced! Very grateful, thank you team!"
"Will worked absolute miracles for me and my partner, my financial situation wasn't great to say the least and I thought there would be absolutely no way that i'd be able to get a mortgage offer. From our first phone call he was so reassuring & positive and I instantly felt a weight had been lifted and that their was finally hope! I don't know how he does it but he managed to secure us a deal within our budget and the whole process was so straight forward. His knowledge is incredible and you can tell he just wants the absolute best for the people he is helping. 100/10 would 100% recommend to anyone I know that is looking to buy without hesitation."
"Mortgage Brokers Near Me has been amazing! Super patient and knowledgeable. We've had two properties fall through, but they've stuck with us every step. Highly recommend!"
"Will is our go-to guy for mortgages for personal and business properties. Excellent communication, very honest and extremely easy to deal with, I couldn't recommend him enough!"


"We've had a great experience with Will at MBNM. An easy flow of conversation to ensure we get the best deal available to us, along with advice and help where needed. Highly recommend!"
Near you, no matter where you are.
Appointed Representative of The Right Mortgage Network (FCA No. 1004260). Company No. 15189091. Registered in England and Wales.