

Near you, no matter where you are.
Appointed Representative of The Right Mortgage Network (FCA No. 1004260). Company No. 15189091. Registered in England and Wales.
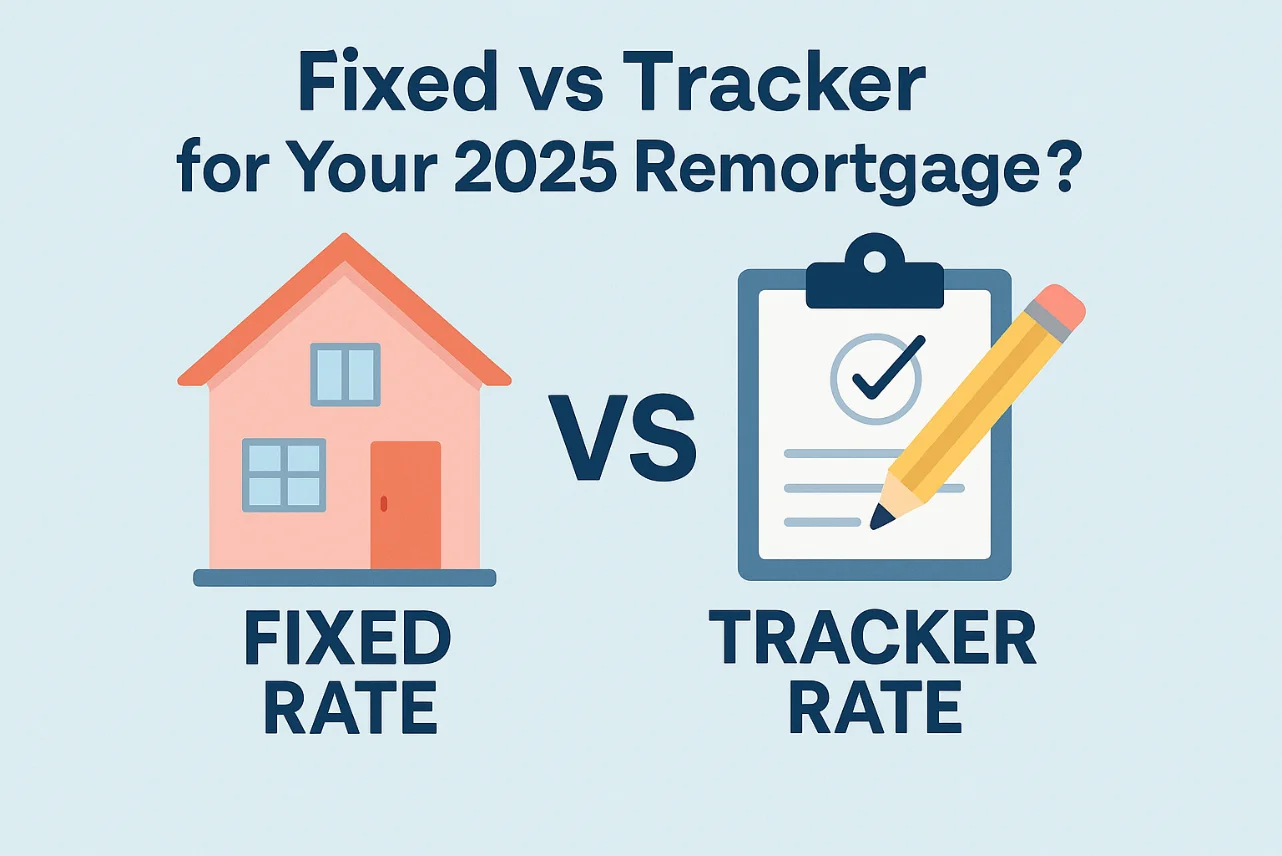
A fixed mortgage gives rate certainty for an agreed period. A tracker can rise or fall with its reference rate. Compare the costs, fees, early repayment charges and payment risks before choosing your next remortgage deal.
Jun 30, 2025
A fixed-rate mortgage keeps your interest rate unchanged for an agreed period. A tracker mortgage follows a reference rate, usually the Bank of England's Bank Rate, with an agreed margin added. Your tracker payments can therefore rise or fall.
For a homeowner remortgaging in 2026, the useful question is how each option fits the household budget, future plans and available deals. Neither type is automatically cheaper or suitable for everyone.
This guide compares their payment risks and practical differences without relying on a rate forecast. Your personal quote will depend on the mortgage balance, property value, loan-to-value (LTV), term and lender criteria.
Start with our remortgage advice service if you want to compare your current lender's offers with other suitable options.
Your rate is agreed for a defined deal period, commonly two or five years, although other periods may be available. On a standard repayment mortgage, scheduled payments are predictable during that period, provided you do not change the loan arrangements.
This can suit a household that needs a known mortgage payment when planning childcare, other bills or savings. It also protects the agreed rate during the deal if wider interest rates rise.
The trade-off is that your existing rate does not automatically fall when market rates fall. Leaving a deal early or overpaying beyond its allowance can trigger an ERC. Check the actual charge schedule and allowance on the offer.
When the fixed period ends, the mortgage commonly moves to the lender's SVR unless you arrange another deal. The fixed deal period is separate from the full mortgage term, which may have many years remaining.
A tracker might be described as the reference rate plus a set margin. For example, a hypothetical deal at “Bank Rate plus 0.75 percentage points” would charge 4.75% if Bank Rate were 4%. These figures explain the calculation and are not current rates or a product offer.
If that reference rate rose by one percentage point, the mortgage rate would normally rise by the same amount under the tracking terms. A fall could reduce the rate, subject to any minimum rate or floor.
Check precisely what the mortgage tracks, the margin, how changes reach your payments, and how long tracking lasts. Some products track for a defined period and then revert to an SVR; a lifetime tracker can work differently.
A minimum rate, sometimes called a collar or floor, can limit how far your rate falls. Ask whether it applies to the reference rate or the total mortgage rate.
Some trackers allow early repayment without an ERC, but that is a product feature to verify. A tracker can still have a product fee, other charges or restrictions. Payment flexibility and rate risk are separate questions.
Ask for both offers in writing. Check each point below against the mortgage illustration, rather than assuming every fixed deal or tracker has the same terms.
A fixed rate gives certainty during the agreed period. A tracker requires enough room in the budget for a higher payment if the reference rate rises.
A fixed deal's existing rate stays the same during its fixed period. A tracker responds to its contractual reference rate, subject to its terms. Neither tells you the future cost of your next deal.
Fixed deals often have ERCs during the deal period. Tracker ERCs vary by product. Compare the actual cost if you expect to sell, switch or repay a large lump sum.
Both types can permit overpayments, but the allowance and any charge depend on the product. Establish how the allowance is calculated and what happens if you exceed it.
Either type can carry a product fee. A no-fee deal may have a higher rate. Include any valuation, legal and advice fees when comparing a product transfer with moving lenders.
Check the reversion rate and review date. Set a reminder early enough to compare your options before a fixed or introductory tracker period expires.
Ask for a comparison using the same loan balance, repayment method, remaining term and time period. A lower payment achieved by extending the term is a different borrowing decision and can increase total interest.
The APRC shown in the mortgage illustration provides a broader comparison of annualised costs over the mortgage term under its stated assumptions. It is not a prediction of future variable rates or a substitute for comparing the period you expect to keep the deal.
Use our mortgage calculator for indicative payments. For a tracker, enter a higher rate as well as the quoted starting rate and consider whether the household could meet that payment alongside other commitments.

Discuss how a fixed deal could fit your budget. Compare the length of the fixed period with your plans to move, repay capital or change income.
Ask about deals with suitable repayment terms and check their ERCs. A tracker with no ERC may provide flexibility, but you still need to manage changing payments and any other costs.
Consider the cash reserve needed for quieter months as well as the rate type. Choosing fixed or tracker does not remove income-evidence and eligibility requirements. Our borrowing power calculator can help you prepare an affordability discussion.
A shorter fix brings the next rate decision sooner and may mean another round of fees. A longer fix gives rate certainty for longer, but its exit terms need to fit your plans. The length of the fix does not by itself determine whether the overall deal is better.
For timings, legal work and product transfers, read how remortgaging works.
No. The starting rates, margin, fees and future reference-rate movements all affect the result. A tracker that starts cheaper can cost more later, while a lower fixed rate can lose its advantage if its fee is high.
Check the named reference rate and tracking terms. A Bank Rate tracker normally follows changes in Bank Rate, but a collar or floor can limit reductions. The lender will apply changes according to the contract.
Potentially. Check the tracker ERC, available switch options, new product fees and eligibility. Some lenders offer a specific track-and-switch feature. There is no guarantee of the fixed rate that will be available when you decide to switch.
Your agreed rate normally stays unchanged for the fixed period. You can review other options, but an ERC and new fees may outweigh any saving from switching before the deal ends.
No. The fixed period controls how long the agreed rate lasts. The full mortgage term is the period over which the loan is repaid and can be much longer. Check both when comparing quotes.
Base-rate changes and future product prices are uncertain. Review offers before your deal ends and include the cost of any time on your lender's SVR. Your decision should fit a payment you can afford and the actual terms available.
Tell us when your current deal ends, the balance remaining and any plans to move or overpay. We can explain suitable fixed, tracker and product-transfer options, check their costs and discuss the payment risks.
Book your first chat with Mortgage Brokers Near Me. The first chat is free. Any fee for later advice or arranging your mortgage will be explained upfront.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Reviewed on 7 October 2026. Illustrations are not current offers. Rates, product terms and lender criteria can change.
Learn how mortgage deposits work, how much you may need, acceptable sources, proof of funds and example deposit amounts for UK property prices.
Read Article
To find a mortgage broker you can trust, shortlist two or three firms, check each one on the FCA Register, and compare their lender access, experience, fees and support. The right broker does not need to be the closest to you if they can advise you remotely and understand your circumstances. Your first chat with MBNM is free, there are no hidden fees, and nothing moves forward until you understand and agree to any fee that may apply.
Read Article
Freehold usually means fewer moving parts, you own the building and the land, you handle maintenance, and there’s no ground rent or service charges. Leasehold means you own the property for a set number of years, and the building (and land) is owned by a freeholder, so you may pay service charges and ground rent, and you can be restricted by the lease. For mortgages, the big “gotcha” is lease length. Once a lease starts getting short (especially heading towards 80 years), it can affect value and lender options, and extending later can get expensive. Reforms are in motion in England and Wales, but you still need to buy based on today’s rules, not headlines.
Read ArticleIf you’re buying, moving, or remortgaging, speak with a MBNM adviser and get clear guidance on what’s realistically available to you, before you commit to anything.
Near you, no matter where you are.
Appointed Representative of The Right Mortgage Network (FCA No. 1004260). Company No. 15189091. Registered in England and Wales.


