Near you, no matter where you are.
Appointed Representative of The Right Mortgage Network (FCA No. 1004260). Company No. 15189091. Registered in England and Wales.
A clear, real-world breakdown of how much you need to earn to buy a £250,000 home in the UK. This guide explains how lenders calculate affordability, how deposit size affects borrowing, what monthly repayments typically look like, and why location plays a huge role in what £250,000 can buy. Written to help first-time buyers sense-check the numbers before making an offer.
Jan 26, 2026

If you are wondering how much you need to earn to get a £250,000 mortgage in the UK, you are asking the right question.
This is one of the most common points where first-time buyers get stuck. People assume a £250,000 home is out of reach because they look at the price, not how lenders actually assess affordability.
The reality is more straightforward than most people expect.
This guide breaks down:
Most UK lenders work on an income multiple of 4 to 4.5 times your household income, depending on circumstances.
Here is what that looks like in practice.
To borrow £225,000, you would typically need a household income of around £37,000 to £40,000.
That lines up with:
So what gives?
The key point is this: income multiples are not the only factor.
Affordability is based on:
For many buyers with clean finances and no major debts, lenders can comfortably support a £225,000 mortgage on an income around £37,500, especially on a joint application.
If you are a single applicant, the maths changes slightly.
As a rough guide:
This is where a lot of people assume they are priced out, even when they are not.
In many cases, adjusting the deposit or choosing the right lender makes the difference.
Using the example above:
You are looking at around £900 to £1,000 per month, depending on the rate and product.
That is important because in many parts of the UK, especially across the North of England, rent for a similar property is often in the same range or higher.
The difference is where the money goes.
Rent pays someone else’s mortgage.
A mortgage pays down your own.
Massively.
A £250,000 budget means very different things depending on where you are buying.
In many northern towns and cities, that figure can buy:
In higher-priced regions, the same budget may only stretch to a small flat.
This is why national affordability headlines often feel misleading. Lenders care about your income, but buyers should care just as much about local property values.
Income is only part of the picture.
Lenders will also look at:
Two people on the same salary can get very different outcomes depending on how their finances are structured.
This is where buyers often get caught out using online calculators alone.
At Mortgage Brokers Near Me, we do not just plug numbers into a calculator and hope for the best.
We:
Our job is not to push you to borrow the maximum. It is to make sure what you buy works long-term.

Buying your first home is not about hitting an arbitrary price point.
It is about understanding:
A £250,000 home is well within reach for many households earning around £37,500. You just need the right advice before you commit.
If you want a clear answer based on your numbers, not assumptions, that is exactly what we help with. Reach out today and Speak to a mortgage adviser.
This article is for general information only and does not constitute mortgage advice. Mortgage availability is subject to lender criteria, affordability checks, and underwriting. Your home may be repossessed if you do not keep up repayments on your mortgage.
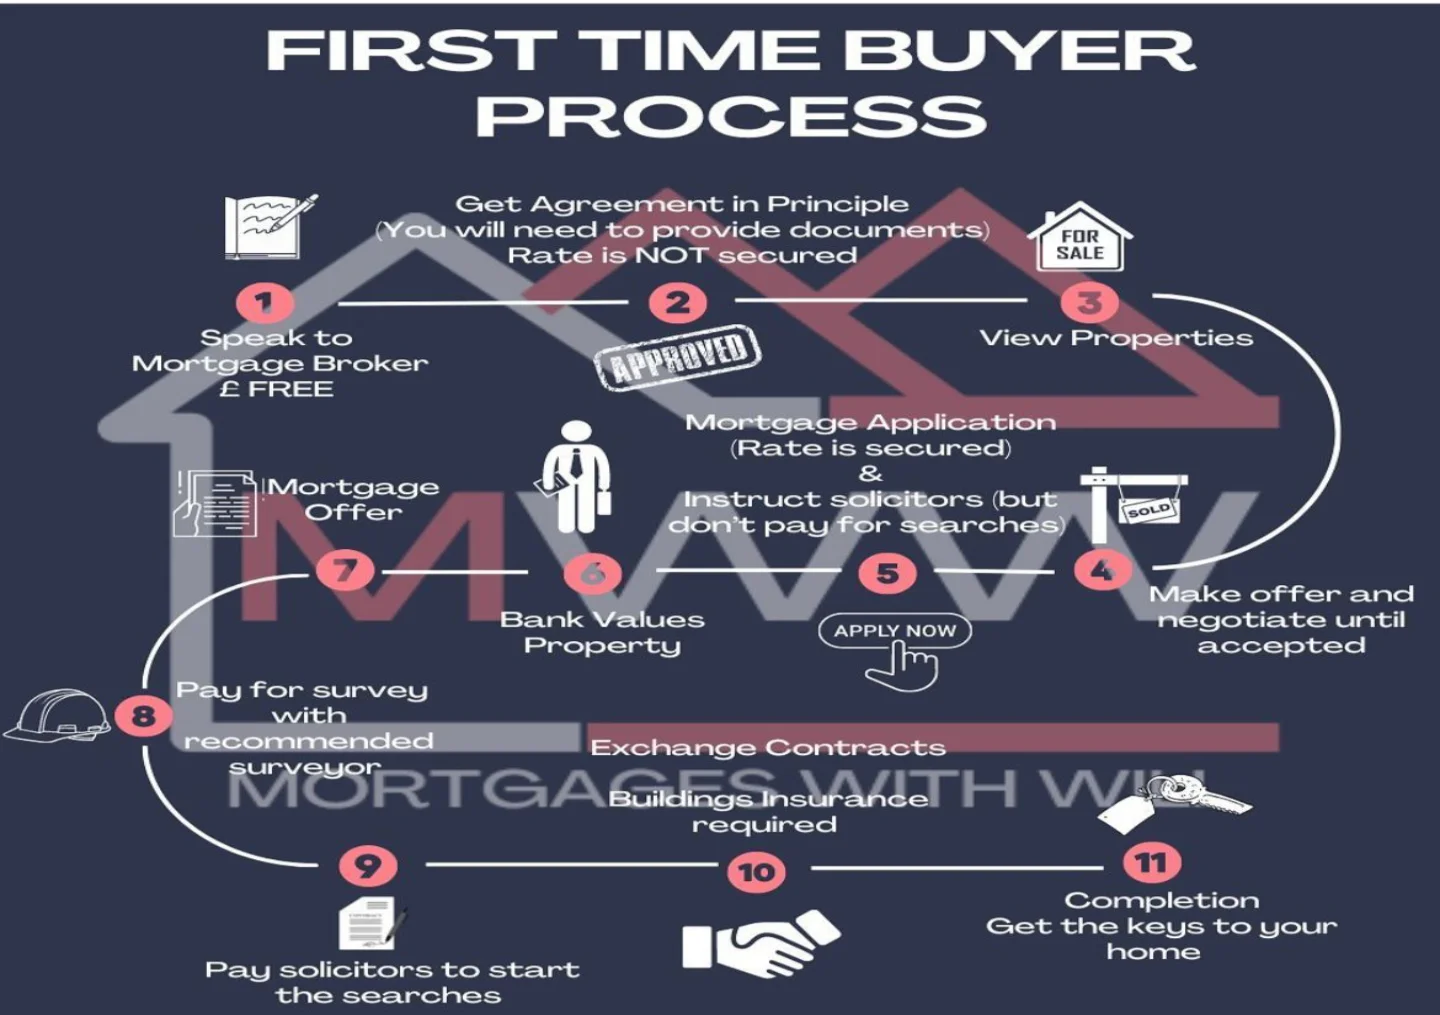
A clear, step-by-step guide to the first-time buyer process, written by Will Sharman of Mortgage Brokers Near Me. Learn what happens at each stage and when to get expert help.
Read Article
If you’re buying your council home through Right to Buy, the discount can sometimes act like your deposit, which means you might not need to save a big cash deposit. But “no deposit” does not mean “guaranteed”. Lenders still check affordability, credit history, the property type, and whether the valuation stacks up. The fastest way to avoid getting messed about is to get the numbers checked properly before you apply, because the wrong lender or the wrong application order can cost you months. Your home may be repossessed if you do not keep up repayments on your mortgage.
Read Article
Is It Cheaper to Use a Mortgage Broker? A Complete Guide for Homebuyers in Kent
Read ArticleIf you’re buying, moving, or remortgaging, speak with a MBNM adviser and get clear guidance on what’s realistically available to you, before you commit to anything.
Near you, no matter where you are.
Appointed Representative of The Right Mortgage Network (FCA No. 1004260). Company No. 15189091. Registered in England and Wales.


